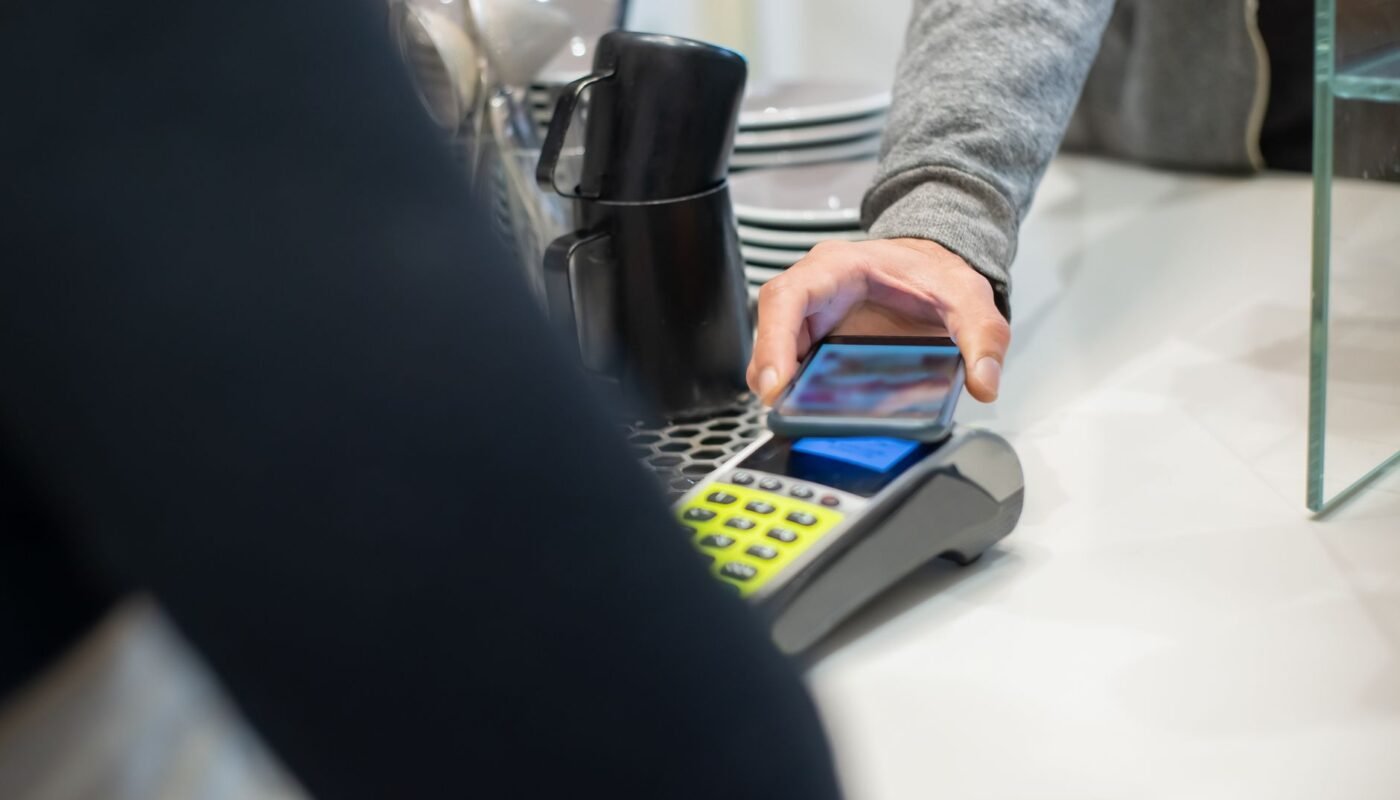

The Competition and Markets Authority has proposed a rule that would require Apple to give UK developers access to iPhone contactless technology through both of the main international standards, on terms the regulator expects to carry substantially lower fees than Apple charges today. The consultation closes on 17 November 2026.
What the CMA is proposing
On 20 October 2026 the CMA published a proposed conduct requirement for Apple’s mobile platform. It covers near field communication (NFC), the radio technology behind tap-to-pay, digital keys and transit passes on a phone. The CMA is using powers under the Digital Markets, Competition and Consumers Act 2024, after it designated Apple as having Strategic Market Status in relation to its mobile platform. The consultation document runs to 147 pages.
The proposed requirement would make Apple provide NFC access to developers on fair, reasonable, transparent and non-discriminatory terms. The CMA splits that into two barriers, technical access and commercial viability.
Advertisement
On technical access, the CMA’s notes to editors name the two main contactless standards used internationally: secure element (SE), which stores information on the device, and host-based card emulation (HCE), which stores data off the device. Apple currently offers only SE in the UK. Under the proposals it would have to offer both. The CMA says the evidence it has seen suggests neither technology raises inherent security concerns.
On commercial viability, the CMA leaves the price itself open and proposes principles for how access charges should be set, with the expectation that charges would be substantially lower than Apple’s current fees while still fairly rewarding Apple for providing access.
The numbers the CMA puts behind it
The CMA cites UK Finance for the scale of contactless: payments made by card or mobile device rose 2% to 19.2 billion in 2025 and now make up 39% of all payments, against 3% a decade ago. For wallet use it cites a 2026 consumer survey by the group Which: 62% of UK adults use a digital wallet, and Apple Wallet, used by 50%, is the most popular. It cites The Data City for the fintech sector, which it puts at 3,348 companies, 362,651 jobs and £213.6 billion in combined turnover.
The CMA also draws a comparison with the EU. Its release says that, unlike in the EU, not a single firm has launched a wallet-type product to compete with Apple’s in the UK. Six months after Apple agreed to provide NFC access for payments in the EU, Vipps launched the first alternative payment app, followed by PayPal, Klarna, Curve and BBVA.
What the regulators said
Sarah Cardell, Chief Executive of the CMA, said: “These proposals open the door to more innovation, more choice and economic growth, including in the UK’s important fintech sector.”
The release also carries a comment from David Geale, who is PSR Managing Director and Executive Director for Consumers, Payments and Competition at the FCA. He said: “Opening up this technology will also support the expansion of open banking, enabling more people to make payments directly from their bank accounts.”
The CMA lists the products it expects access could support: digital wallets and payment services, digital IDs and age-verification tools, digital car, hotel and workplace keys, tickets and travel passes, and loyalty and rewards services. The consultation page adds one procedural point. Any non-disclosure agreement a party has with Apple should not prevent it from responding, and Apple has confirmed it will not use any other confidentiality provision to stop a party responding.
Where this sits in the wallet market
This site has tracked the wallet market from the merchant side. In August we reported that retailers’ in-house cards are joining digital wallets, and that Walmart’s wallet reversal ended retail’s last holdout. Both stories involved merchants adding their cards to the wallets that already dominate phones. The CMA proposal concerns the other side of the same relationship: who is allowed to build a wallet-type product on the phone in the first place.
In our reading, the proposal matters most for firms whose product is a payment or an identity credential that today has to live inside someone else’s wallet. The CMA’s own list of use cases, from account-to-account payments to digital IDs, points that way. Whether any of them becomes viable depends on the part the CMA has left open, the price. The regulator has set an expectation of substantially lower charges and has not named a figure, so the fee evidence submitted in the consultation will shape the outcome.
What it means for the finance leader
For a bank, issuer or payments firm with a UK customer base, the proposal does not change anything yet. It is a consultation, and the CMA will make a final decision after it has assessed the responses. Three things are worth doing before 17 November.
- Work out which of your products depend on iPhone NFC access today, and what Apple currently charges you or your partners for it. The CMA’s expected direction is lower fees, so the baseline is the number to know.
- List the use cases you have shelved because only SE access was available. HCE access is the change that would reopen them.
- Decide whether to respond. The CMA says it has already heard from businesses that current terms may not be commercially viable. The consultation is open to responses from any business.
The consultation closes at 11:59pm on 17 November 2026. The full document is on the CMA case page for Apple’s mobile platform.